
1 – 11 February 2027
Alexander Marynych (Kyiv School of Economics) will give a mini-course in Kyiv on Poisson point processes, with the option to join online. The course is intended for undergraduate or graduate students with some basic knowledge of probability, as well as for anyone interested in related topics. Lectures will be given in English.
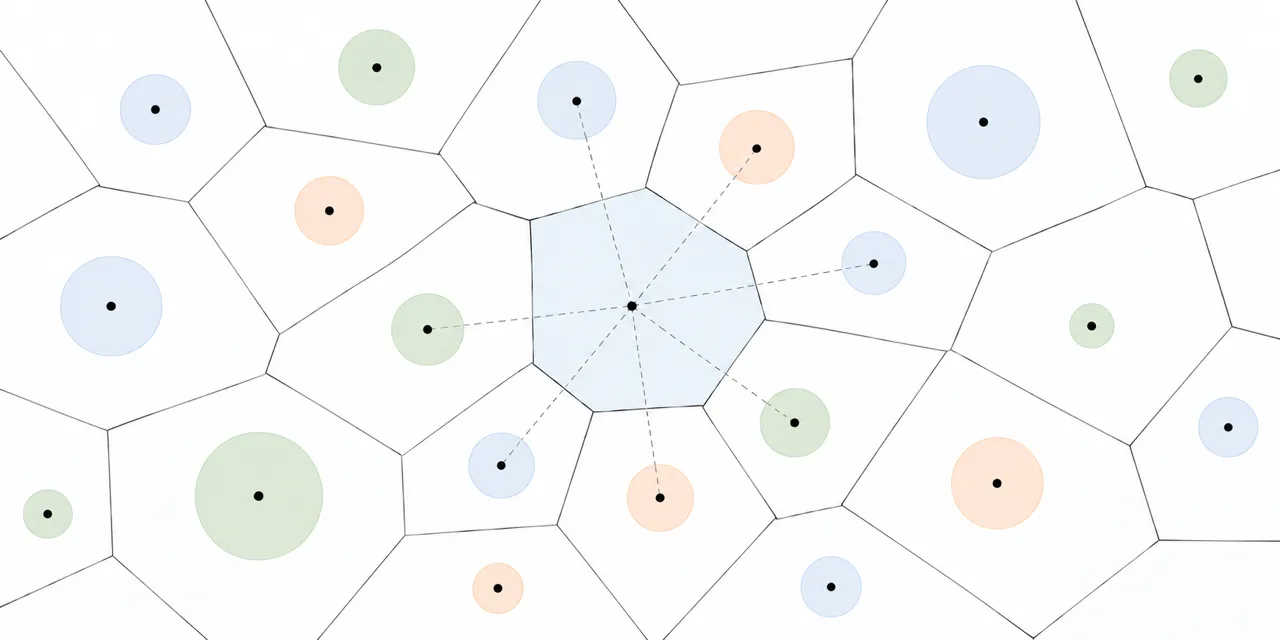
This four-lecture mini-course provides an introduction to Poisson point processes with an emphasis on the tools most useful in stochastic geometry. We shall discuss their construction on general state spaces and develop fundamental results such as the superposition, mapping and marking theorems, Campbell’s formula and the Laplace functional. Homogeneous and inhomogeneous Poisson processes on the real line and on the plane will serve as basic examples. The final part of the course will illustrate the theory through classical models of stochastic geometry including Poisson line processes and the Boolean model of random sets.
Alexander Marynych is a Professor in the Department of Mathematics at Kyiv School of Economics. He got Master's degree in Mathematics from Taras Shevchenko National University of Kyiv in 2008, obtained a PhD in Mathematics from Utrecht University (the Netherlands) in 2011, and earned the degree of Doctor of Physical and Mathematical Sciences from Taras Shevchenko National University of Kyiv in 2017. Prof. Marynych’s research interests lie in the fields of probability theory and stochastic processes, specifically focusing on limit theorems for random processes, random discrete structures, the probabilistic analysis of algorithms, and stochastic geometry.
Teaching Assistant: Mykyta Sadok (Taras Shevchenko National University of Kyiv)
ICMU Working Space
Kyiv School of Economics (KSE), Campus Obolon
19 Obolonska Naberezhna, Kyiv, Ukraine
Online participation available
Artem Dudko (Institute of Mathematics of Polish Academy of Sciences)
Oleksiy Klurman (University of Bristol)
Oleksandr Tsymbaliuk (Purdue University)